Net Worth Tracking for Beginners: What to Measure & Why
Net Worth Tracking for Beginners: What to Measure & Why
You check your bank account on payday and feel a quick sense of relief. Money came in, bills are getting paid, and you might even have a little left over for the weekend. But a few weeks later, the balance is low again. This cycle leaves many young professionals wondering if they are actually making any financial progress.
To understand your true financial health, you need to look beyond your income and measure what you actually keep. Net worth tracking for beginners answers this problem directly: by calculating your total assets minus your total liabilities, you get a single, accurate number that reveals your true financial progress over time.
Income tells you what you make in a given month. It's a flow of money. But income alone doesn't tell you if you're building financial security. Net worth tracking takes all your different financial decisions (spending, saving, borrowing, and investing) and boils them down into a single number. For beginners, tracking this number is a crucial step in taking control of your money.
What is Net Worth? Understanding Assets and Liabilities
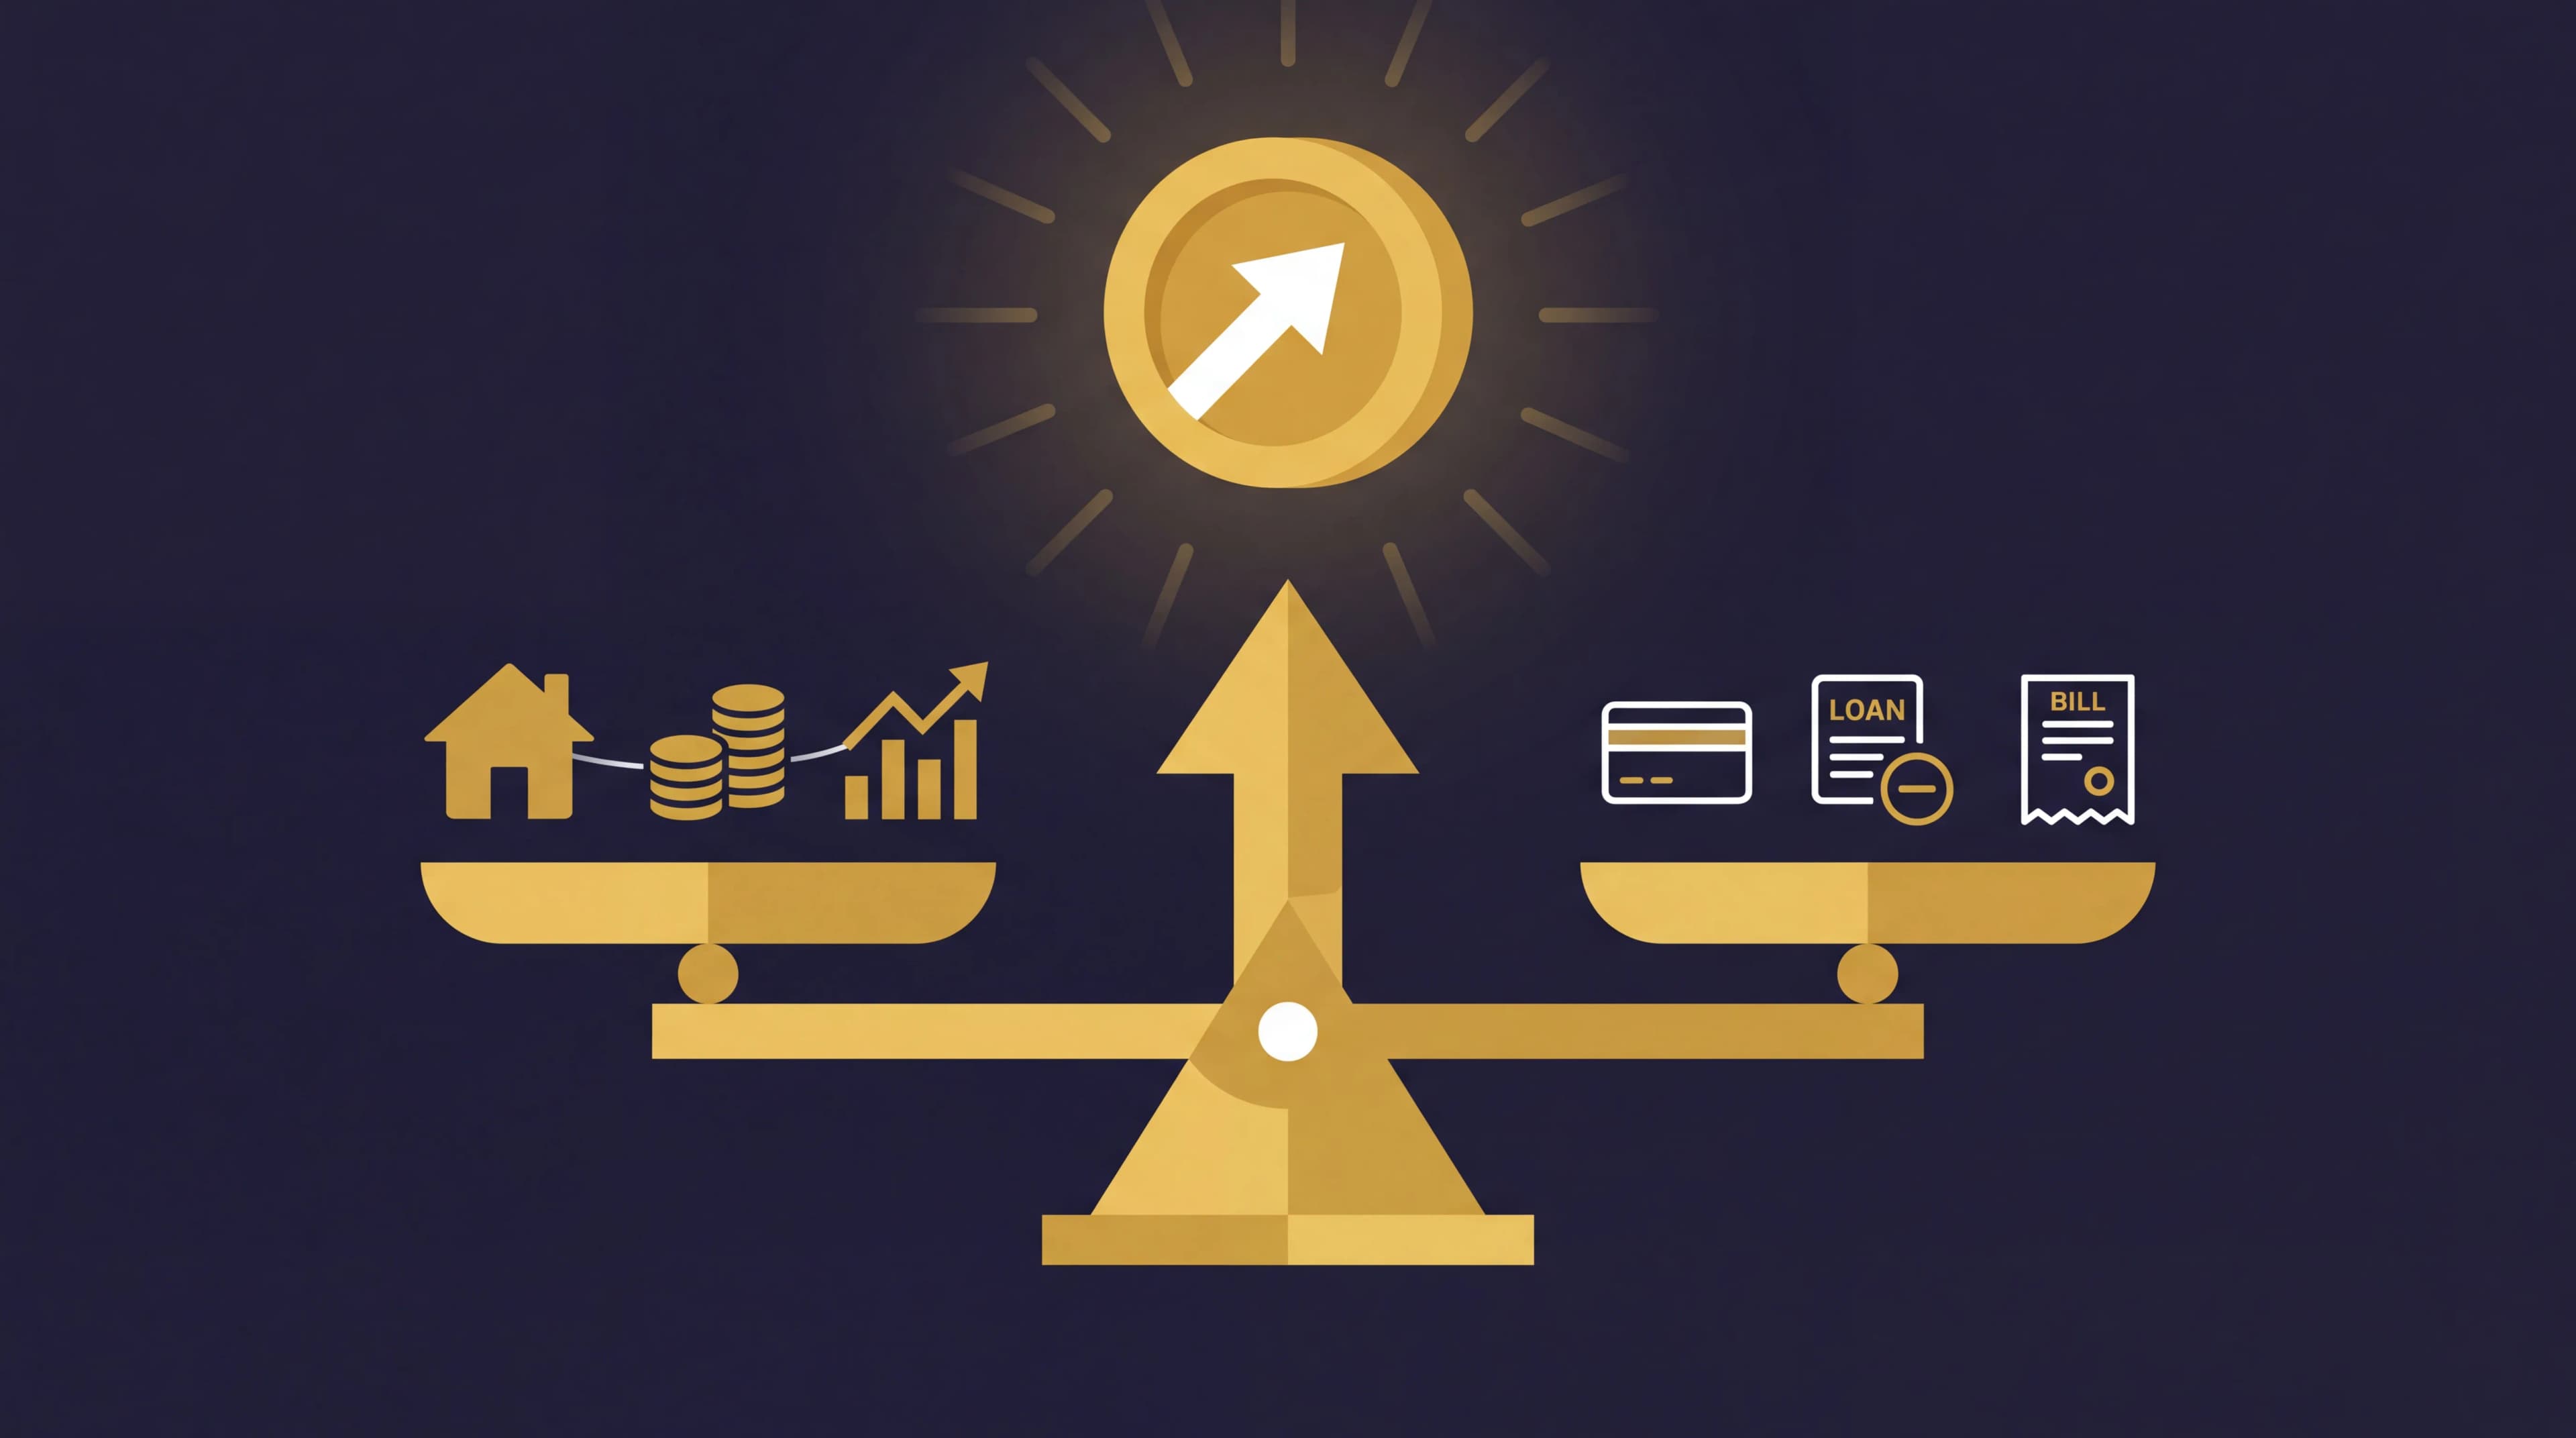
Net worth — the total value of your financial resources minus your total debts — is a common way to measure your accumulated wealth. The math is incredibly straightforward. Your net worth is simply your total assets minus your total liabilities.
Assets — everything you own that holds value — include cash in your checking and savings accounts, plus investments in retirement accounts. It also covers the current market value of your car and the value of a home if you own one.
Liabilities — everything you owe to someone else — include student loans, credit card balances, personal loans, car loans, and mortgages.
When you subtract your liabilities from your assets, you get your net worth. Many people get overly focused on their income because it's visible and immediate. A higher salary feels like success. But behavioral economists note that wealth (your net worth) is what actually provides a buffer against life's surprises. Tracking your net worth shifts your attention away from short-term cash flow and points it toward long-term stability.
The bottom line: Your net worth is simply a snapshot of exactly where you stand financially on the day you do the math.
Why a Negative Net Worth is Normal for Beginners
One of the biggest hurdles for beginners is the fear of seeing a negative number. Maybe you recently graduated and have student loans. Or perhaps you had to rely on credit cards to get through a tough year. In these cases, your liabilities will likely be higher than your assets.
This means your net worth will be negative.
If your net worth is below zero, you haven't failed. A negative net worth is entirely normal early in your career. According to the Federal Reserve (2022), the 10th percentile of net worth for households under age 35 is around -$13,060. This means roughly one in ten young households have debts that exceed their assets by at least that amount.
Understanding this helps remove the shame around debt. Net worth isn't a grade on your character. It's just a diagnostic tool. When you start tracking it, the current number matters far less than the direction it's moving. If you have a net worth of -$30,000 this year and -$20,000 next year, you've made a massive $10,000 improvement.
Seeing that negative number shrink is often the motivation people need to build a strategy to pay off debt when starting from zero. The goal is progress, not perfection.
Here's what this means: A negative net worth isn't a failure; it's simply a starting point that shows you exactly how much debt you need to conquer.
Average vs. Median Net Worth: What the Data Says
It's natural to wonder how you compare to everyone else, but looking at average net worth numbers can be highly misleading.
According to the Federal Reserve's Survey of Consumer Finances (2022), the mean (average) household net worth was roughly $1,063,700. But that number is heavily skewed by a small percentage of extremely high-wealth households.
A much more accurate benchmark is the median net worth. The median represents the exact middle point. Half of households have more, and half have less. According to the Federal Reserve's Survey of Consumer Finances (2022), the median U.S. household net worth was approximately $192,900.
Median Net Worth by Age
Age plays a massive role in these numbers. Wealth accumulation takes time, so older households naturally have higher net worths than younger ones. Here's how the median net worth breaks down by age group based on the Federal Reserve data:
- Under age 35: $39,000
- Ages 35 to 44: $135,300
- Ages 45 to 54: $246,700
- Ages 55 to 64: $364,270
- Ages 65 to 74: $409,900
For a beginner in their twenties or early thirties, a median of $39,000 helps set realistic expectations. It shows that substantial growth is possible early on, but it also proves you don't need hundreds of thousands of dollars to be doing fine for your age.
It's also important to understand the role of housing. Primary residences represent more than a quarter of all U.S. household assets. When you exclude home equity from the calculation, the median U.S. household net worth drops drastically from $192,900 to about $57,900. If you're currently renting, your net worth will naturally look lower than a homeowner's because you don't have that specific asset. This is normal and expected.
The bottom line: Comparing yourself to the median net worth for your age group provides a much more realistic benchmark than looking at skewed national averages.
The Role of Emergency Savings in Net Worth Tracking
While net worth gives you the big picture, it doesn't tell you if you're prepared for an emergency next week. You can't easily pay a medical bill with the equity in your house or the funds in your retirement account. You need liquid cash.
This is why tracking your cash buffers alongside your overall net worth is so important.
According to the Federal Reserve's Survey of Household Economics and Decisionmaking (2024), 55 percent of U.S. adults reported having enough savings to cover three months of expenses. But 18 percent said they could cover less than $100 of an unexpected expense using only their savings.
On top of that, roughly 31 percent of adults couldn't cover a $500 unexpected expense from savings alone. They would have to rely on credit cards, borrow from family, or sell something.
Private surveys show similar anxiety. According to Bankrate's Annual Emergency Savings Report (2024), nearly six in ten U.S. adults (59 percent) are uncomfortable with their level of emergency savings.
When you track your net worth, you should always keep a separate eye on your liquid assets. Your retirement accounts might be growing beautifully, but if your checking account is empty, you're financially vulnerable. Many beginners start by asking why the traditional 3-month emergency fund might be dead. But the first step is simply getting one month of expenses safely tucked away in a savings account.
Here's what this means: While your overall net worth tracks long-term wealth, you must maintain liquid emergency savings to protect yourself from short-term financial shocks.
Turning Net Worth Tracking Into Financial Action
Net worth and emergency savings don't grow by accident; they are the result of daily and monthly behaviors, specifically budgeting and saving.
According to Debt.com's annual budgeting survey (2024), more than eight in ten Americans now use some form of budget. Among those who budget, over 86 percent report that keeping track of their income and expenses has helped them get out of or stay out of debt.
Despite the popularity of budgeting, actual savings rates remain low. According to the Federal Reserve (2023), the average personal savings rate in the United States was about 4.4 percent of disposable income. Financial experts typically recommend saving at least 10 to 20 percent of your income.
This gap between average behavior and recommended behavior is where tracking your net worth becomes incredibly useful. When you calculate your net worth every few months, you get immediate feedback on your budget. If your net worth is staying flat or going down, your current budgeting strategy needs an adjustment. If your net worth is climbing, you know your habits are working.
If you've never tracked your money before, a great starting point is to build your first budget in 30 minutes. A budget manages your daily flow of money so that your long-term net worth can grow.
The bottom line: Tracking your net worth provides the ultimate feedback loop for your monthly budgeting and saving habits.
The Power of a Written Financial Plan
There's a strange disconnect in personal finance right now. Many young professionals feel confident about their financial future, but very few have actually written down a plan to get there.
According to Charles Schwab's Modern Wealth Survey (2024), more than 60 percent of Americans believe they're in a better position to achieve their financial goals than previous generations. They point to better access to investing and more financial education online.
Yet, the same survey reveals that only 36 percent of Americans have a written financial plan.
Here's the most important part of that survey. Among the people who actually have a written plan, three out of four say it makes them feel more in control of their finances. Even better, 96 percent of those with a plan report feeling confident they will reach their financial goals.
Tracking your net worth is the foundation of a written financial plan. It takes the abstract worry out of your head and puts concrete numbers on a page. When you write down your assets and liabilities, the mystery disappears. You know exactly what you're dealing with, which drastically reduces financial anxiety.
Here's what this means: Documenting your net worth is the crucial first step in creating a written financial plan that builds lasting confidence.
How to Start Tracking Your Net Worth Today
You don't need complicated software or a degree in finance to track your net worth. A simple piece of paper or a basic spreadsheet is all you need.
Here's a practical way to start.
Step 1: Calculate Your Total Assets
First, list your assets. Check the balances of your checking and savings accounts. Log into your workplace 401(k) or personal IRA and write down the current balance. If you own a car, look up its estimated private party value on a site like Kelley Blue Book. Add all of these numbers together. This is your total asset number.
Step 2: Calculate Your Total Liabilities
Second, list your liabilities. Log into your student loan servicer and find the current payoff amount. Do the same for any credit cards, personal loans, or auto loans. Add all of these balances together. This is your total liability number.
Step 3: Find Your Net Worth Number
Finally, subtract your total liabilities from your total assets. Write this final number down, along with today's date. You've just calculated your net worth.
Don't check this number every day or even every week. Daily market fluctuations will make your investment balances bounce around, which can be stressful and distracting. Instead, update your net worth spreadsheet once a quarter or twice a year. This timeframe is long enough to see the real impact of your debt payments and savings contributions.
Over time, you'll start to see a trend. As you pay down your student loans, your liabilities will shrink. As you automatically transfer money into savings each month, your assets will grow. Watching that gap widen in your favor is one of the most satisfying experiences in personal finance.
The bottom line: You don't need to check your net worth daily; updating your numbers once a quarter is the perfect cadence to track meaningful financial progress.
Common Questions
How often should I calculate my net worth?
You should calculate your net worth once a quarter or twice a year. Checking it too frequently can cause unnecessary stress due to normal daily market fluctuations. A quarterly check-in provides enough time to see the real impact of your savings and debt payoff efforts.
What is a good net worth for a beginner?
A good net worth for a beginner depends heavily on your age and whether you own a home, but a realistic benchmark for adults under 35 is the median of $39,000. If you recently graduated with student loans, having a negative net worth is completely normal and expected. The most important metric is that your number is consistently moving in a positive direction.
Should I include my car in my net worth?
Yes, you should include the current market value of your car as an asset when calculating your net worth. However, you must also include any outstanding auto loan balance as a liability. You can use tools like Kelley Blue Book to find an accurate estimate of your vehicle's current private party value.
Why is my net worth negative?
Your net worth is negative because your total liabilities (what you owe) are currently higher than your total assets (what you own). This is a very common scenario for young professionals who have student loans, credit card debt, or auto loans but haven't had time to build significant savings. As you pay down debt and save money, your net worth will eventually cross into positive territory.
Your One Next Step
Don't wait for the perfect time to organize your finances. Grab a piece of paper or open a blank spreadsheet right now. Take 15 minutes to log into your accounts. Write down your total assets, write down your total liabilities, and subtract what you owe from what you own. Save this number with today's date, and set a calendar reminder to do the exact same math three months from today.
Your Money. Your Terms.
Listen to this article
AI-generated audio · Voices by ElevenLabs
Get smarter about money
One practical tip per week. No spam, no hype — just clear steps toward financial progress.

Sammy Dynamo
Software Engineer | CS Student | Technopreneur, Dyxium Inc
Related Articles
12 min read
Personal DevelopmentWhat to Ask a Financial Advisor: A Young Pro’s Checklist
Not sure what to ask a financial advisor? From fees to fiduciary duty, use this checklist...
Sammy Dynamo
11 min read
Personal DevelopmentAdult Children at Home: Protect Your Retirement
Having adult children at home is common, but it shouldn’t ruin your finances. Ready to share...
Sammy Dynamo
11 min read
Personal DevelopmentUpskill While Working: Beat the Reskilling Crisis
With 59% of workers needing new skills by 2030, you must adapt. Discover how to upskill...
Sammy Dynamo