Seeing that first real paycheck hit your bank account is a major milestone. You finally have income that reflects your hard work and education. According to the U.S. Bureau of Labor Statistics (2024), median weekly earnings for full-time workers aged 25 to 34 sit around $1,136. That translates to roughly $59,000 a year.
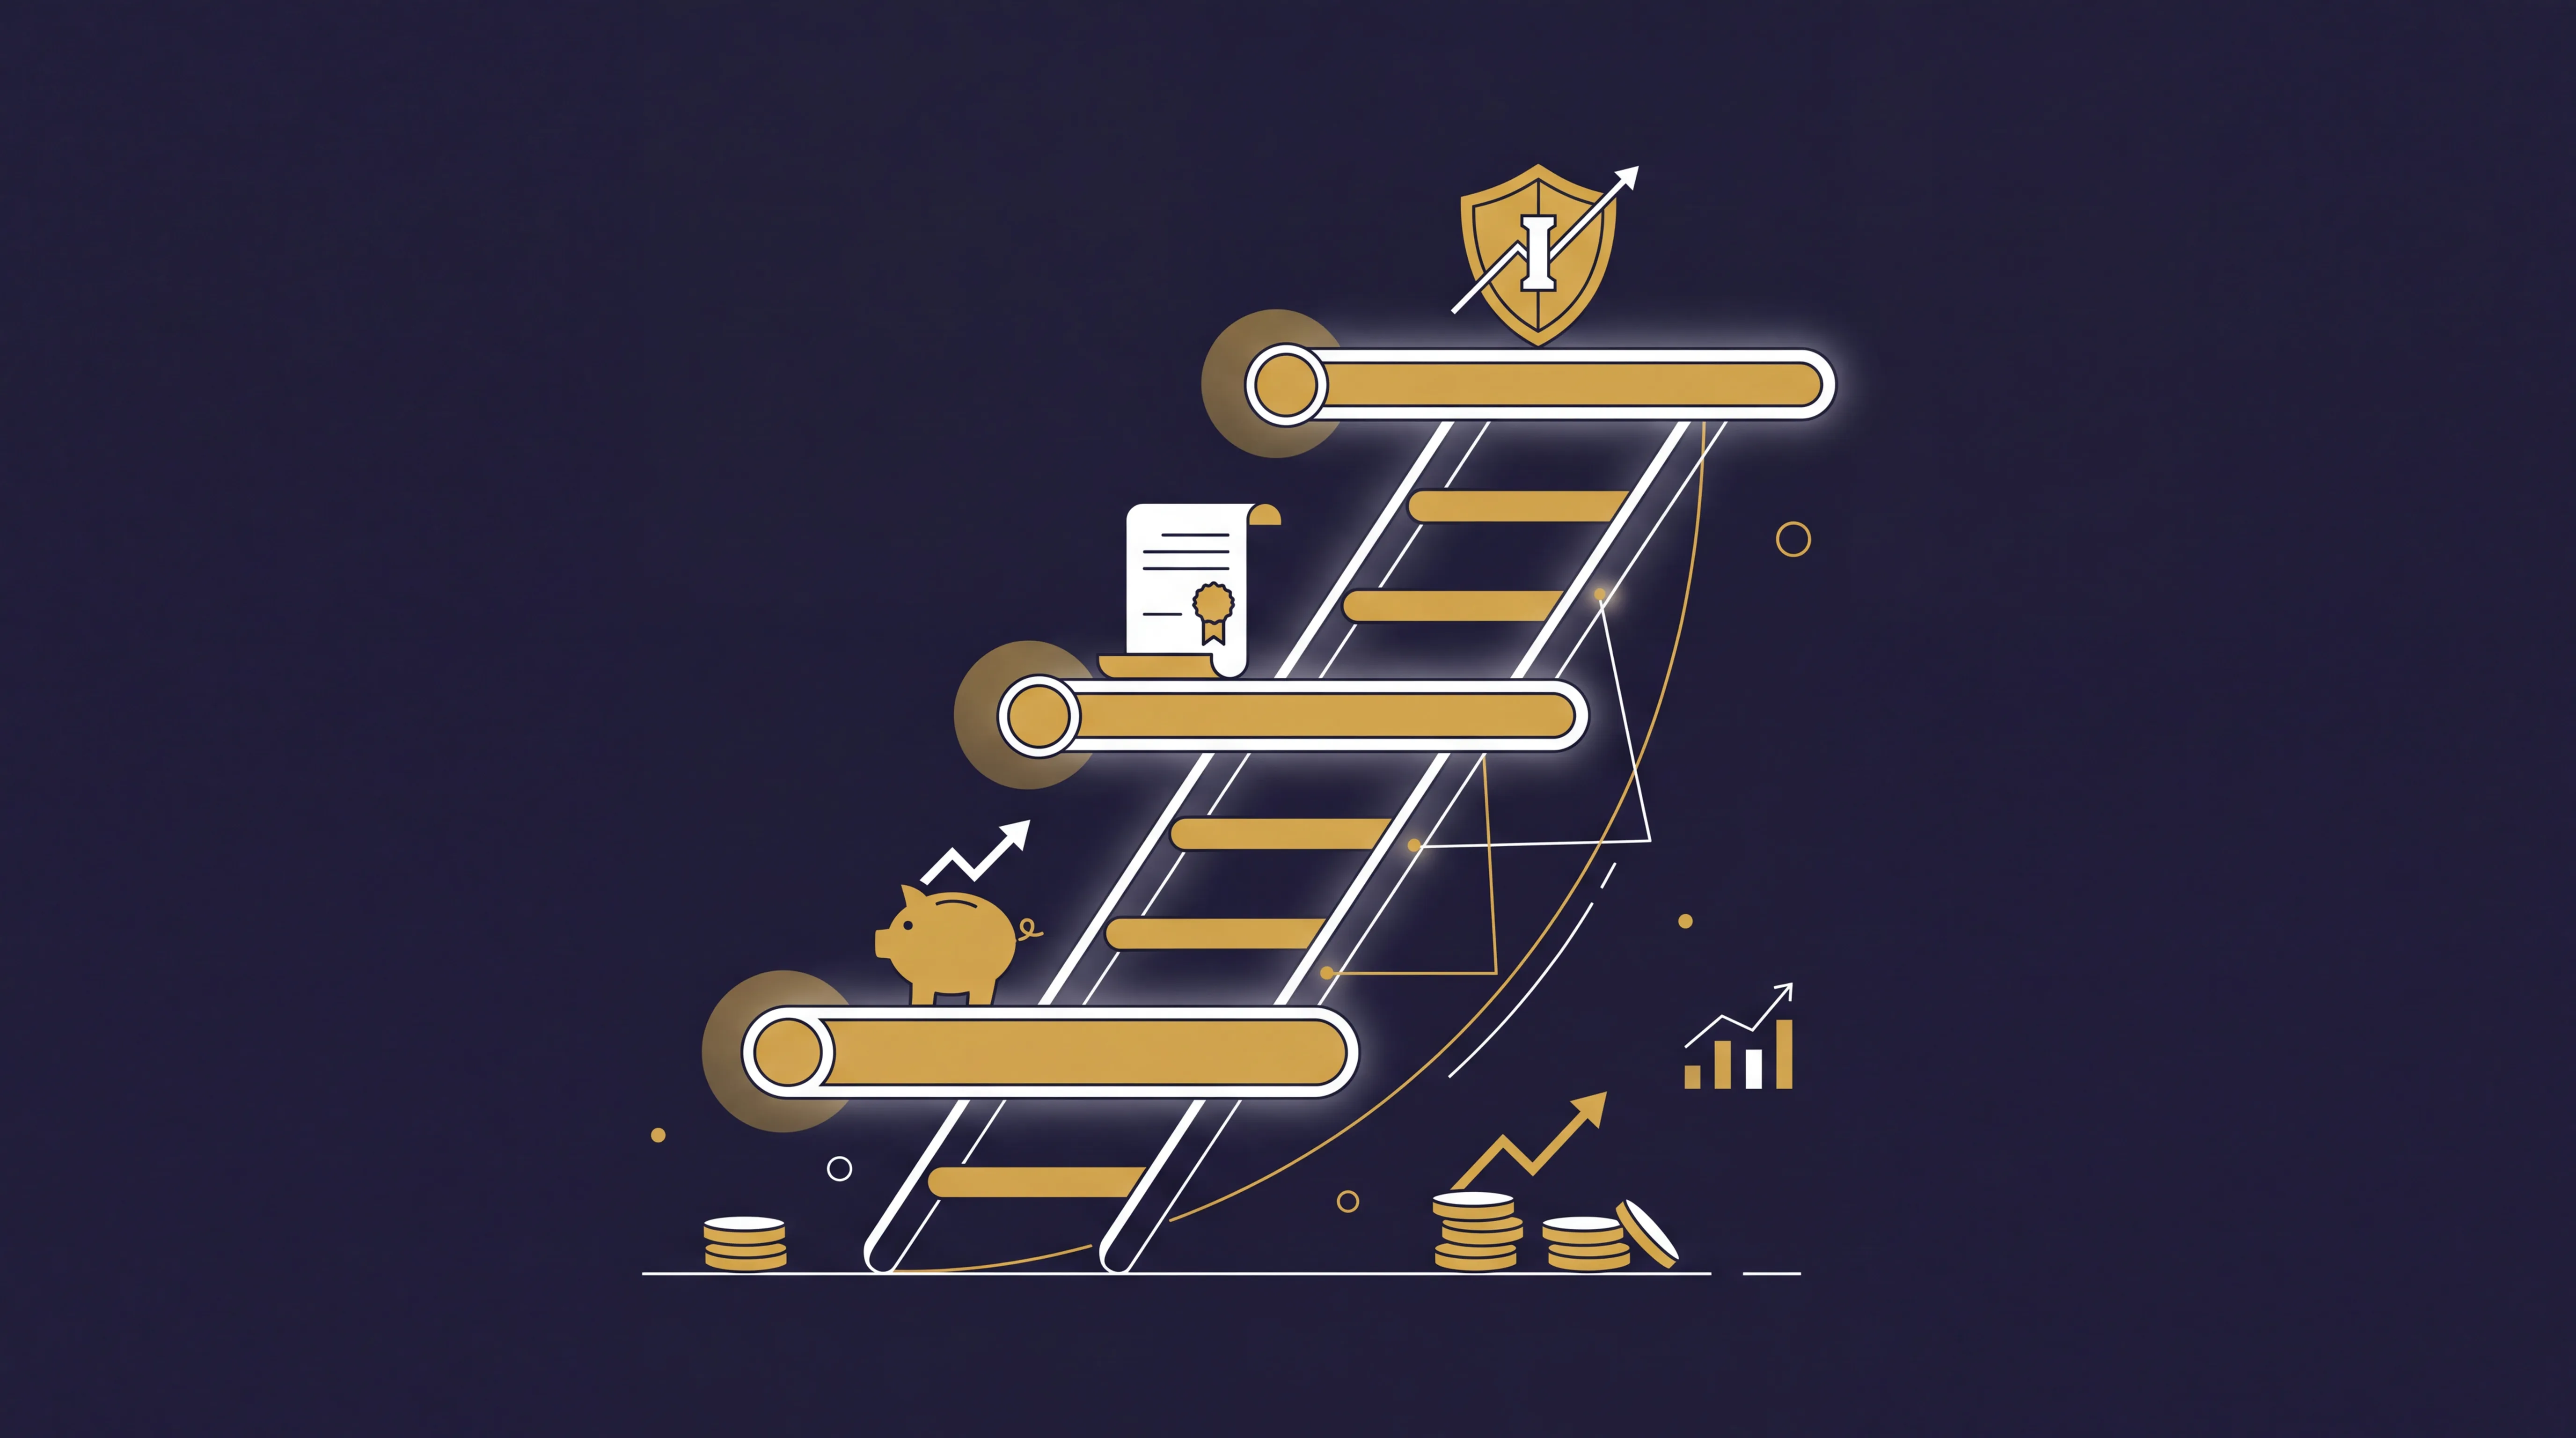
It feels like a massive amount of money until rent, groceries, student loans, and utilities take their cut. Suddenly, that exciting deposit shrinks, and you are left wondering what you should actually do with the remainder. What should you do with your first real paycheck? You should immediately route your money through a financial order of operations: build a starter emergency fund, capture your employer match, pay off high-interest debt, expand your savings, and begin long-term investing.
Financial order of operations — a prioritized, step-by-step sequence for allocating your income to maximize wealth and minimize risk.
Having a clear sequence for your money takes the guesswork out of your finances. You do not need a complicated spreadsheet or a degree in economics to get this right. By following a proven sequence, you can build security, pay down debt, and start investing without feeling overwhelmed.
Here is exactly how to direct your first real paycheck, based on the latest 2026 financial data.
The Reality Behind Managing Your First Paycheck
Managing your first paycheck requires balancing immediate desires with long-term financial security. Before we get into the steps, it helps to understand the financial environment you are entering. Many young professionals feel pressure to immediately buy nice clothes for the office, upgrade their apartment, or go out to expensive dinners to celebrate.
This pressure is completely normal. According to the Walton Family Foundation (2023), 44 percent of Gen Z individuals frequently compare themselves to others, and 49 percent care deeply about what others think of them. This social comparison easily spills over into our spending habits.
However, giving in to that pressure early on can lead to serious regrets. According to NerdWallet and The Harris Poll (2024), 69 percent of Americans have financial regrets for the year. The youngest adults were the most likely to express remorse. What were they regretting? Nearly 30 percent regretted not saving for emergencies, and 25 percent regretted overspending on entertainment.
Having a financial order of operations protects you from these common traps. It ensures your money goes toward your actual priorities rather than fleeting social expectations.
The bottom line: Prioritizing a financial plan over social pressure prevents early money regrets and sets the foundation for lasting wealth.
Step 1: Build a Starter Emergency Fund Buffer
The absolute first thing you should do with your extra paycheck money is build a small cash buffer to prevent new debt.
We live in a time where financial fragility is incredibly common. According to Bankrate (2024), 27 percent of U.S. adults have no emergency savings whatsoever. If their car breaks down or they need an unexpected medical procedure, they have to rely entirely on credit cards or loans.
According to the Federal Reserve (2024), 63 percent of adults could cover a $400 unexpected expense with cash, savings, or a credit card paid off promptly. That sounds okay until you look at slightly larger emergencies. According to FINRA (2024), 35 percent of adults probably or certainly could not come up with $2,000 in a month if an unexpected need arose.
Your first goal is to get yourself out of that vulnerable 35 percent. Aim to save $1,000 to $2,000 in a high-yield savings account as quickly as possible. This is not your full emergency fund. It is just a starter buffer to keep you from going into debt when minor life accidents happen.
If you are not sure where to find that initial cash, reading our guide on building a $1,000 emergency fund in 90 days can help you break the goal down into manageable weekly chunks.
Here's what this means: Saving a quick $1,000 to $2,000 acts as a financial shock absorber, keeping minor emergencies from becoming high-interest debt.
Step 2: Capture Your 401(k) Employer Match
Capturing your employer match is the most critical investing step because it guarantees an immediate return on your money. Once you have your starter buffer, look at your workplace benefits. If your employer offers a 401(k) or similar retirement plan with a matching contribution, you need to participate.
Employer match — a benefit where your company contributes money to your retirement account based on the amount you contribute.
If they offer to match 100 percent of your contributions up to 5 percent of your salary, contributing that 5 percent doubles your money instantly. There is no investment anywhere else in the world that guarantees a 100 percent return on day one.
Starting this habit with your very first paycheck is incredibly powerful. According to Northwestern Mutual (2025), Americans believe they need about $1.26 million to retire comfortably. That number sounds intimidating, but the math changes drastically depending on when you start.
According to their calculations, assuming a 7 percent annual return, someone starting at age 20 would need to invest about $330 per month to reach that $1.26 million target by age 65. If you wait until age 30 to start, the required monthly amount jumps to $695. Waiting until age 40 pushes it to over $1,500 a month.
By claiming your employer match immediately, you are doing the heavy lifting early. You might even hit that $330 monthly target just between your own small contribution and your employer's match.
The bottom line: Contributing enough to get your full employer match is non-negotiable if you want to build long-term wealth without leaving free money on the table.
Step 3: Pay Off High-Interest Debt
Eliminating high-interest debt is the fastest way to free up your monthly income for wealth building. After securing your starter emergency cash and your employer match, direct your focus to high-interest debt. This usually means credit cards or personal loans with interest rates above 8 or 10 percent.
Credit card debt is a massive roadblock for young earners. According to Bankrate (2025), 33 percent of Americans have more credit card debt than they have in emergency savings. This creates a cycle where you are constantly paying past bills rather than funding your future.
Mathematically, paying off a credit card that charges 24 percent interest is exactly the same as earning a guaranteed 24 percent return on your investments. You will never find a stock or mutual fund that safely guarantees that kind of growth.
List out your high-interest debts. You can use the avalanche method (paying the highest interest rate first) to save the most money, or the snowball method (paying the smallest balance first) to get a quick psychological win. The method matters less than the action. Attack this debt aggressively with every spare dollar from your paycheck.
Here's what this means: Paying off credit cards and high-interest loans provides a guaranteed double-digit return on your money and frees up cash flow.
Step 4: Expand to a Fully Funded Emergency Safety Net
A fully funded emergency safety net transforms a financial crisis into a mere inconvenience. With bad debt out of the way, you can breathe a little easier. Now it is time to turn that $1,000 starter buffer into a proper emergency fund.
The standard advice is to save three to six months of essential living expenses. Essential expenses include rent, groceries, utilities, insurance, and minimum debt payments. You do not need to save enough to cover your dining out or vacation budgets.
Most people know they need this safety net, but few actually build it. According to Bankrate (2024), 89 percent of Americans say they would need at least three months of expenses saved to feel comfortable. Yet, only 44 percent actually have that amount saved. According to FINRA (2024), just 46 percent of adults have rainy-day funds covering three months of expenses.
Building this fund takes time. If you bring home $4,000 a month and your essential expenses are $2,500, your three-month target is $7,500. Do not panic if it takes you a year or more to reach this goal. The peace of mind you get from knowing you can handle a job loss or a major medical event is entirely worth the wait.
For a realistic look at what you should aim for as you progress through your twenties, you can check out our real 2026 goals for how much to save by 30.
The bottom line: Expanding your savings to cover three to six months of essential expenses protects your investments and keeps you out of debt during major life disruptions.
Step 5: Begin Consistent, Long-Term Investing
Consistent, long-term investing is the primary engine for building generational wealth and achieving financial independence. Once your three-month safety net is fully funded, you have reached a major turning point. You are no longer just playing defense against emergencies and debt. You can finally start playing offense by investing more of your income.
The Importance of Investing Consistency
Younger generations are actually doing a great job of starting early. According to Charles Schwab (2024), 58 percent of Americans are investing today. Gen Z respondents reported an average starting age of 19 for saving and investing, which is much younger than previous generations.
However, starting is only half the battle. Consistency is where people struggle. According to FINRA (2024), the proportion of young adults (under 35) who invest actually fell from 32 percent in 2021 to 26 percent in 2024. Many young people jumped into the market during a hype cycle and then stopped contributing when the economy felt uncertain.
Your goal is to be boring and consistent. You can increase your 401(k) contributions beyond the employer match, open a Roth IRA, or start putting money into a standard brokerage account. Focus on low-cost index funds that track the broader market.
You do not need thousands of dollars to begin this step. Setting up an automatic transfer on payday is the best way to ensure it happens. If you are wondering how to make this work on a tight budget, our blueprint on how to start investing with $50 a month offers a great starting point.
Here's what this means: Automating your investments into low-cost index funds ensures you steadily build wealth regardless of market hype or economic uncertainty.
Step 6: Protect Your Financial Progress With Insurance
Adequate insurance coverage is the defensive shield that protects your accumulated wealth from catastrophic loss. The final step in your financial order of operations is protecting the life you are building. It is not an exciting topic, but it is a necessary one.
According to Northwestern Mutual (2025), 61 percent of Gen Zers say they place too much emphasis on building wealth and growing assets without dedicating enough attention to protecting those assets.
If you rent an apartment, you need renter's insurance. It usually costs less than $15 a month and protects everything you own from fire, theft, or water damage. If you have a car, make sure your auto insurance liability limits are high enough to actually protect you if you are at fault in a major accident. Finally, ensure you are enrolled in a solid health insurance plan, whether through your employer or the open market.
Skipping insurance to save a few dollars a month is a massive risk. One bad accident or emergency room visit can wipe out your emergency fund and put you right back into high-interest debt. Treat insurance premiums as a non-negotiable part of your monthly budget.
The bottom line: Maintaining proper health, auto, and renter's insurance prevents a single unexpected disaster from wiping out years of financial progress.
The Value of a Written Financial Plan
A written financial plan removes emotion from money management and provides a clear roadmap for every dollar you earn. Following these steps naturally creates a financial plan. This puts you ahead of the curve. According to Charles Schwab (2024), while more than 60 percent of Americans feel they are in a better position to achieve their financial goals than previous generations, only 36 percent actually have a written financial plan.
You do not need a fifty-page document to be successful. Your plan can simply be a checklist on your phone that says:
- Save $1,000.
- Get the 401(k) match.
- Pay off the credit card.
- Save three months of expenses.
- Invest 15 percent of my income.
When you get a raise or a bonus, you just look at your checklist. Wherever you are on the list, that is where the extra money goes. It removes the emotion and the decision fatigue from managing your money.
Here's what this means: Documenting your financial order of operations gives you a simple, stress-free system for allocating future raises and bonuses.
Common Questions
What is a financial order of operations?
A financial order of operations is a prioritized, step-by-step sequence for managing your money. It tells you exactly where to allocate your income—such as building an emergency fund, paying off debt, and investing—to maximize wealth and minimize risk.
How much of my first paycheck should I save?
You should aim to save at least 20 percent of your first paycheck, following the popular 50/30/20 budgeting rule. However, your immediate priority should be routing enough cash to quickly build a $1,000 to $2,000 starter emergency fund.
When should I start investing my paycheck?
You should start investing your paycheck immediately to capture any employer 401(k) match, as this is essentially free money. Beyond the match, wait to invest heavily until you have paid off high-interest debt and built a three-month emergency fund.
Why is paying off debt prioritized over investing?
Paying off high-interest debt is prioritized over investing because credit card interest rates typically exceed stock market returns. Eliminating a debt with a 24 percent interest rate provides a guaranteed 24 percent return on your money, which no safe investment can match.
Your One Next Step
Log into your bank account or payroll portal today and set up an automatic transfer for your next payday. Even if it is just $25 moving from your checking account to a separate high-yield savings account, you are officially taking action on Step 1. Building financial confidence does not require massive, immediate changes. It just requires you to direct your money with intention, one paycheck at a time.
Your Money. Your Terms.